The Catizona Cattler
Money Matters: What Can I Keep in Arizona Bankruptcy? (2026)
Arizona's 2026 Exemption Table, Explained by My Dad
Reviewed by Jeff A. Biddle, Arizona bankruptcy attorney
Jump to the 2026 Exemption Table ↓
Call now: (480) 622-4987 Send the Bankruptcy Cats Signal
My desk is covered in printouts, and every website has a different number for the car, the bank account and the house. So I did what any good reporter does when the numbers don't match. I took the whole pile to my dad, Businessman, the accounting cat at Jeff Biddle Law. He sorted it into three stacks in about four seconds: "Old number. New number. Number somebody typed wrong."
Here's what he told me.
The Short Answers
Debit: Can I keep my house in an Arizona bankruptcy in 2026?
Biz: Arizona protects home equity up to a cap, about $437,600 for 2026 as calculated under the statute's formula. It protects the equity, not the home's total value, and it doesn't stop the mortgage lender from foreclosing if the payments stop.
Debit: Can I keep my car in an Arizona bankruptcy?
Biz: Equity in one vehicle, up to about $16,500 for 2026, or about $27,500 if the debtor or a dependent has a physical disability. Equity is the value minus what's owed on the loan.
Debit: How much money can I keep in my bank account?
Biz: One account, up to about $5,600 for 2026. Not $300. We'll get to that one.
Debit: Are retirement accounts protected in Arizona bankruptcy?
Biz: 401(k)s, IRAs and similar plans are protected under Arizona law, except for money put in within 120 days before filing.
Debit: How much household furniture and goods can I keep?
Biz: Up to about $16,500 for 2026, all of it added together.
Debit: Are tools of the trade protected in Arizona bankruptcy?
Biz: $5,000. That number is printed in the statute, and the statute has no yearly adjustment for it.
Debit: Do Arizona bankruptcy exemption amounts change every year?
Biz: Four of them go up every January with inflation. So always check the date on any table you read, including ours.
1. What Is an Exemption, and Which List Does Arizona Use?
Debit: Okay, start at the very beginning. What is an exemption?
Biz: An exemption is a rule that says a certain kind of property, up to a certain amount, is protected from creditors. When someone files bankruptcy, their property becomes part of what's called the bankruptcy estate. The exemptions are the list of what the filer gets to protect from that estate.
Debit: Is there one list for the whole country?
Biz: There's a federal list in the Bankruptcy Code, but Arizona has opted out of it. Arizona law says plainly that residents of this state are not entitled to the federal exemptions in 11 U.S.C. § 522(d). So Arizona residents use Arizona's list, found mostly in Title 33 of the Arizona Revised Statutes.
Debit: What if someone just moved here from somewhere else?
Biz: Good question, reporter. Which state's list applies depends on where the person was domiciled, meaning where they made their true home, for the 730 days before filing. That's two years. If they didn't live in just one state that whole time, the law looks at where they lived for most of the 180 days before that two-year stretch.
Debit: So a cat who just moved to Chandler might not use the Arizona list yet?
Biz: Possibly. Jeff checks that first.
2. Why Does Every Website Show a Different Exemption Number?
Debit: Here's my big question. Why does every website have a different number?
Biz: Because Arizona's exemption amounts aren't frozen anymore. Back in 2022, the law set new base amounts: $400,000 for the home, $15,000 for household goods, $15,000 for a vehicle ($25,000 with a disability) and $5,000 for one bank account. Then each of those four statutes added a rule: starting January 1, 2024, and every January 1 after that, the amount gets adjusted by the increase in the Consumer Price Index, rounded up to the nearest $100.
Debit: How do they measure the increase?
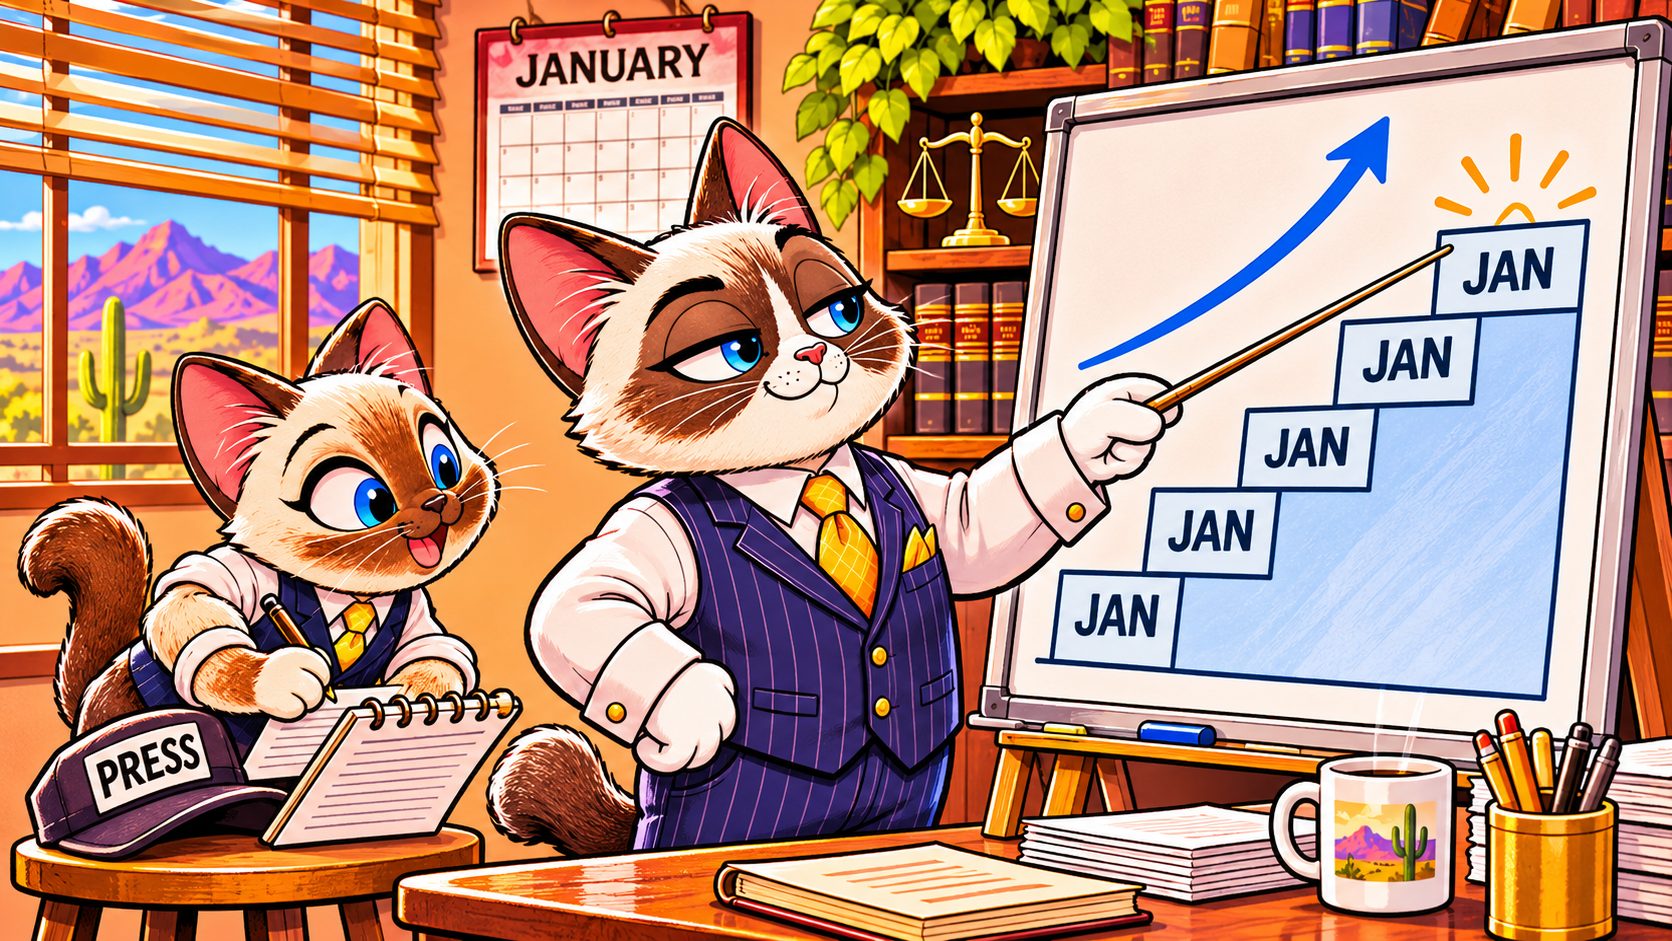
Biz: The statute uses the CPI-U, a price index from the federal Bureau of Labor Statistics, comparing one August to the August before. Here's the trick, though. The statutes print the base number and the formula. They don't print the new number. So the 2026 amounts are calculated by running that formula. Watch the homestead climb: $400,000 became $414,700 for 2024, then $425,200 for 2025, then $437,600 for 2026.
Debit: Like a staircase!
Biz: A staircase with a new step every January. That's why I always say: date every number.
Debit: So the pages with $15,000 for the car...
Biz: Some 2026 pages still show $15,000 for the vehicle. That's the original 2022 number, before the yearly adjustments. It's not right for 2026. And one page claims bank accounts are protected only up to $300. That's wrong for 2026 too. The statute itself prints $5,000, and that number has been adjusted since.
Debit: Can I see all the numbers in one place?
Biz: Here's the master table.
Arizona Exemption Table, as of January 1, 2026
Last checked November 19, 2026
| Property | Statute base amount | 2026 amount (calculated under the statute's CPI formula) | A.R.S. cite | Adjusts every January? |
|---|---|---|---|---|
| Homestead equity | $400,000 | $437,600 | § 33-1101 | Yes |
| Household furniture, goods, electronics, appliances (combined fair market value) | $15,000 | $16,500 | § 33-1123 | Yes |
| Equity in one motor vehicle | $15,000 | $16,500 | § 33-1125(8) | Yes |
| Equity in one motor vehicle, physical disability of debtor or dependent | $25,000 | $27,500 | § 33-1125(8) | Yes |
| One bank account at one financial institution | $5,000 | $5,600 | § 33-1126(A)(9) | Yes |
| Tools of the trade (combined fair market value) | $5,000 | $5,000 | § 33-1130(1) | No adjustment clause in the statute |
| Prepaid rent or security deposit (only if no homestead is claimed) | $2,000 | $2,000 | § 33-1126(C) | No adjustment clause in the statute |
| Retirement plans: 401(k), 403(b), IRAs, Roth IRAs, 457 and similar | No dollar cap in state law | No dollar cap in state law | § 33-1126(B) | Not applicable |
| Wearing apparel | $500 | $500 | § 33-1125(1) | No (not adjusted for inflation) |
| Engagement and wedding rings | $2,000 | $2,000 | § 33-1125(4) | No (not adjusted for inflation) |
| Firearms | $2,000 | $2,000 | § 33-1125(10) | No (not adjusted for inflation) |
| Library ($250), one watch ($250), musical instruments ($400), and one typewriter, computer, bicycle, sewing machine, family bible or burial lot ($2,000 total) | $250 / $250 / $400 / $2,000 total | $250 / $250 / $400 / $2,000 total | § 33-1125(2), (5), (6), (7) | No (not adjusted for inflation) |
| Pets and domestic animals; professionally prescribed prostheses, including a wheelchair or motorized mobility device | No dollar cap | No dollar cap | § 33-1125(9), (11) | Not applicable |
| Life insurance proceeds payable to a surviving spouse or child (not the policy's cash value) | $20,000 | $20,000 | § 33-1126(A)(1) | No (not adjusted for inflation) |
| Wages (weekly disposable earnings) | A creditor may reach only the lesser of 10 percent, or the amount above 60 times the highest applicable minimum hourly wage | Same formula | § 33-1131 | Not applicable |
| Social Security and public benefits | Exempt under federal and state law; keep uncommingled | Exempt under federal and state law; keep uncommingled | 42 U.S.C. § 407(a); § 33-1126 | Not applicable |
| 529 college savings plans | Exempt, except contributions made within 2 years before filing | Exempt, except contributions made within 2 years before filing | § 33-1126(A)(10) | Not applicable |
| Inheritances and windfalls | Property you become entitled to within 180 days after filing can become part of the estate | Property you become entitled to within 180 days after filing can become part of the estate | 11 U.S.C. § 541(a)(5) | Not applicable |
Married couples: each spouse gets their own personal property exemptions and can combine them or use them separately (A.R.S. § 33-1121.01), but the homestead is one per married couple and does not double.
Call now: (480) 622-4987 Send the Bankruptcy Cats Signal
Debit: Are these numbers per person or per couple?
Biz: Per person for personal property—cars, household goods, clothing, bank accounts and the rest. Under Arizona law, each spouse gets their own personal property exemptions, and a married couple can combine them on the same asset or use them on different ones. The homestead is the one big exception: one per married couple, no doubling.
Debit: Why do you keep saying "calculated"?
Biz: That's what these 2026 figures are: the statute's formula applied to the federal price data. Since they're calculated, the exact number for your case is something to confirm with Jeff before you file. Then, next January, the four amounts that adjust go up again.
3. Can I Keep My House? Home Sweet Equity
Debit: Let's talk houses. How much of a home is protected?
Biz: The homestead exemption protects the equity up to the cap, about $437,600 for 2026 as calculated. It protects the equity, not the home's total value. Equity is what the home is worth minus what's owed on it.
Debit: So if the house is protected, the bank can't take it?
Biz: No, and this is a rule people miss all the time: the homestead protects your equity from other creditors, not from the mortgage lender. If the payments stop, the lender can still foreclose. The law also lists other liens the homestead doesn't stop, like a mechanic's lien from someone who worked on the house, or a lien for back child support.
Debit: Does it have to be a regular house?
Biz: Nope. Arizona's homestead covers a house, condo, co-op, mobile home, manufactured home, park model, motor home, travel trailer, fifth wheel or houseboat, plus the land the home sits on. That's thanks to a 2025 update in Arizona law (SB 1540), which overrode an Arizona Supreme Court ruling (In re Drummond) so motor homes, trailers and houseboats are explicitly covered. The catch is you have to actually live in it as your residence—a vacation RV still falls under the vehicle exemption.
Debit: If two married cats own the house, do they get double?
Biz: No. It's one homestead per single person or married couple. It doesn't double—unlike personal property exemptions such as cars, clothes, household goods and bank accounts, where each spouse gets their own.
Debit: What if someone sells their house?
Biz: The money from the sale stays protected for 18 months, or until they set up a new homestead, whichever comes first. But cash someone pulls out in a refinance is not covered.
Debit: What if the house goes up in value after filing?
Biz: In a bankruptcy, the homestead is measured on the filing date. If the equity is within the cap on that day, any increase in value during the case is fully protected.
Debit: Any catch for a brand-new house?
Biz: One federal rule. If the home equity was acquired within 1,215 days before filing, which is about three years and four months, a federal cap of $214,000 can apply for cases filed on or after April 1, 2025. There's an exception for equity rolled over from an earlier Arizona home bought before that window. How that works for any one family is a question for Jeff.
4. Can I Keep My Car, Furniture and Clothes?
Debit: Now the car. Can someone keep it?
Biz: Arizona protects equity in one motor vehicle, up to about $16,500 for 2026, or about $27,500 if the debtor or a dependent has a physical disability.
Debit: What if they owe more on the car than it's worth?
Biz: Then there's no equity to protect. Just like with a house, the exemption protects the equity, not the car's total value, and it doesn't stop the lender from repossessing if the payments stop.
Debit: What about the couch? And the TV? And my scratching post?
Biz: Household furniture, furnishings, goods, consumer electronics and appliances are protected up to about $16,500 for 2026, all added together. The statute measures that by fair market value. Think of what the things are worth today, not what they cost new.
Debit: What about Mom's wedding ring?
Biz: The statute has a list of personal items with their own caps, and these are not adjusted for inflation. Clothing up to $500. Engagement and wedding rings up to $2,000. Musical instruments up to $400. A library up to $250. One watch up to $250. Firearms up to $2,000. Horses, milk cows and poultry up to $1,000. And one typewriter, computer, bicycle, sewing machine, family bible or burial lot, up to $2,000 total.
Debit: A typewriter? Who has a typewriter?
Biz: The law has been around a while, son. A few things have no dollar cap at all: professionally prescribed prostheses for the filer or a dependent, including a wheelchair or motorized mobility device, and all pets and domestic animals.
Debit: ALL pets?!
Biz: All pets. You can stop checking on yourself now.
Debit: Any rule about how they're used?
Biz: They have to be used mainly for personal, family or household purposes.
5. How Much of My Bank Account Is Protected?
Debit: Okay, settle it. Is the bank account protection $300 or $5,600?
Biz: For 2026, about $5,600 as calculated under the statute's formula. The statute prints a base of $5,000 for money in one account at one financial institution, and it has been adjusted every January since 2024. Tables that say $300 are wrong for 2026. Older tables showed a much lower figure, and that number stuck on some websites like an old note on the fridge.
Debit: Is it every account added up?
Biz: No. It's a single account. And it doesn't protect the money from the bank's own normal service charges.
Debit: What about money that comes from somewhere special, like Social Security?
Biz: Social Security benefits get their own protection under federal law. The statute says they aren't subject to garnishment or to the operation of any bankruptcy law. Child support and spousal maintenance received under a court order are also protected under Arizona law, although that doesn't stop a creditor collecting child support itself.
Debit: What if that money is in the same account as everything else?
Biz: Mixed money can get complicated fast. If benefits and other money share an account, that's something to go over with Jeff before filing. And please don't move money around on your own before you talk to him.
6. Are Retirement Accounts and Insurance Protected?
Debit: Is a 401(k) safe?
Biz: Arizona protects retirement plans like 401(k)s, 403(b)s, 457 plans, traditional IRAs and Roth IRAs, with no dollar cap in state law.
Debit: There's always a catch, isn't there?
Biz: You're learning. The catch is timing. Money put into those plans within 120 days before filing is not protected. So a big last-minute deposit into a retirement account doesn't get the same shield.
Debit: What about life insurance?
Biz: A few pieces here. Money payable to a surviving spouse or child on the life of a deceased spouse, parent or guardian is protected up to $20,000. Separately, the cash surrender value of a life insurance policy that has been owned for two years and names a spouse, child, parent, brother or sister (or a dependent family member) as beneficiary is protected. Annuities owned for two years are protected too, with similar beneficiary rules. So are health, accident and disability benefits.
Debit: Wait, so the $20,000 isn't the cash value?
Biz: Right. The $20,000 is for proceeds paid to a survivor. People mix those up all the time.
Debit: What about college savings? I'm going to be a very educated kitten.
Biz: A 529 college savings plan is protected, except money put in within two years before filing.
7. Are My Work Tools and Paychecks Protected?
Debit: What about a cat who runs a little business? Tools, a laptop, a website?
Biz: Tools of the trade are protected up to $5,000 in combined fair market value. That covers tools, equipment, instruments and books, and also things like phone numbers, client lists, marketing tools, websites and domain names. It applies to the debtor or the debtor's spouse. That $5,000 is printed in the statute, which has no adjustment clause for it.
Debit: Is a car a tool if I drive to work?
Biz: Not if it's used mainly for personal or household transportation. That car goes under the vehicle exemption instead. For someone whose main income is farming, there's a separate $2,500 for farm machinery, animals and feed. And arms and uniforms someone is required by law to keep are fully protected.
Debit: What about paychecks?
Biz: Arizona limits how much of a paycheck a creditor can garnish. From weekly disposable earnings, a creditor can reach only the lesser of 10 percent, or the amount above 60 times the highest applicable minimum hourly wage. That limit doesn't apply the same way to child support orders, Chapter 13 bankruptcy orders or state and federal tax debts. Garnishment gets its own Money Matters column, so stay tuned.
8. What Timing Traps Can Cost Me Property, Including Tax Refunds?
Debit: Okay, Dad, what can go wrong?
Biz: Mostly timing. Let's go through the clock.
Biz: 120 days: retirement contributions made within 120 days before filing aren't protected. Two years: 529 contributions made within two years before filing aren't protected. 1,215 days: home equity acquired in that window can face the federal $214,000 cap. And 180 days after filing: if someone becomes entitled to an inheritance, life insurance proceeds or property from a divorce within 180 days after filing, it can become part of the bankruptcy estate. (In a Chapter 13 case the window can run longer. Ask Jeff.)
Debit: What about tax refunds?
Biz: Arizona protects the part of a refund that comes from the earned income tax credit and child tax credits, federal or state. Specifically, the protected amount is the lesser of the total refund or the credits claimed on the return. Tax refunds get their own Money Matters column, too.
Debit: What if someone has more equity than the cap?
Biz: Then the part above the cap isn't protected. That's exactly the kind of thing Jeff looks at before anyone files.
Debit: What's the biggest trap?
Biz: Doing something big right before filing without asking first. A big purchase, a sale, or moving money or property to someone else. Any of those can change the picture. So the rule in our house is simple: call Jeff before you move or buy anything big.
Summary
Debit: Can you sum it all up, Dad?
Biz: Here's the whole column on one shelf, as of January 1, 2026:
- Arizona residents use Arizona's exemption list, not the federal one, if Arizona was home for the 730 days before filing (with a special rule for people who recently moved).
- Four amounts adjust every January under the statute's CPI formula. For 2026, as calculated: homestead equity about $437,600; household goods about $16,500; one vehicle about $16,500 (about $27,500 with a qualifying disability); one bank account about $5,600.
- Tools of the trade ($5,000) and prepaid rent ($2,000) have no adjustment clause in the statute.
- Retirement plans have no dollar cap in Arizona law, except contributions made within 120 days before filing.
- Exemptions protect the equity, not the property's total value, and they don't stop a lender from foreclosing on a home or repossessing a car if the payments stop.
- Married couples can double personal property exemptions (cars, household goods, clothing, bank accounts and more) by combining them or using them separately. The homestead does not double.
- Pages showing $15,000 for the vehicle or $300 for the bank account are wrong for 2026.
- Date every number, because the four adjusting amounts change again every January.
Debit: And the most important part?
Biz: No table can promise what any one family keeps. Every case is different. Before filing, and before moving or buying anything big, call Jeff and have him run your list.
Debit: This has been Debit, for the Catizona Cattler. Money matters!
--- ---
Keep reading
- Behind on Car Payments in Arizona? Chapter 13 Can Generally Help You Keep Your Car
- A Whirlwind Date with Chapter 7
- A Long-Term Relationship with Chapter 13
- Can Mortgage Mediation in Chapter 13 Lower Your Payment in Arizona?
- The Debting Game: Chapter 7, Chapter 13, or a Debt Program?
- All Bankruptcy Cats blog posts
Flare Explains
Flare, Ember's kitten, breaks down the big words, in the order they appear in the column.
Exemption: A rule that protects a certain kind of property, up to a set amount, from creditors and from being sold in a bankruptcy case.
Bankruptcy estate: The property a person owns when they file bankruptcy, which the case gathers together. Exempt property is protected from that estate.
Domicile: A person's true, permanent home. Arizona's exemption list applies if Arizona was the filer's domicile for the 730 days before filing. Recent movers can fall under a different rule. Jeff checks this first.
every January
CPI-U (Consumer Price Index): A federal measure of how much everyday prices have gone up. Arizona uses it each January to adjust four exemption amounts.
UP UP UP
Rounded up to the nearest $100: After the yearly inflation math, any amount that isn't already an even hundred is rounded up to the next hundred dollars.
Homestead: The home a person lives in, which can be a house, condo, mobile home, manufactured home, motor home, travel trailer, fifth wheel or houseboat, plus the land under it.
Equity: What property is worth minus what is still owed on it. Exemptions protect the equity, not the property's total value.
Lien: A legal claim against property that secures a debt. A mortgage or car loan is a lien the owner agreed to.
Foreclose / repossess: When a lender takes back a home (foreclosure) or a car (repossession) because the loan payments stopped. An exemption does not prevent either.
Fair market value: What property would sell for today, rather than what it cost new.
Aggregate: All added together. The household-goods limit is for everything combined, not for each item.
Garnishment: A court process that lets a creditor take part of a person's wages or money held by someone else, such as a bank.
Disposable earnings: The part of a paycheck left after deductions required by law, such as taxes. Garnishment limits are figured from this amount.
Pebbles of Information
Rocky, the firm's research cat, dug up where all of this comes from.
Arizona statutes (azleg.gov)
- A.R.S. § 33-1101, Homestead exemption (including motor homes, travel trailers, fifth wheels and houseboats as residence, subsection (A)(3)); annual CPI adjustment, subsection (D); bankruptcy measured on filing date, subsection (F)
- 2025 Ariz. Sess. Laws ch. 111 (SB 1540), amending A.R.S. § 33-1101 to explicitly cover motor homes, travel trailers, fifth wheels and houseboats
- A.R.S. § 33-1103, Liens the homestead does not stop
- A.R.S. § 33-1101(C), Homestead cash proceeds of a sale protected 18 months or until a new homestead is established, whichever is shorter; not refinance proceeds
- A.R.S. § 33-1121, Definitions
- A.R.S. § 33-1121.01, Availability of exemptions for married persons (each spouse gets personal property exemptions, which may be combined or taken separately)
- A.R.S. § 33-1123, Household furniture, goods, electronics and appliances; annual CPI adjustment, subsection (B)
- A.R.S. § 33-1125, Personal property items, subsections (1)–(7) and (9)–(11); one motor vehicle, subsection (8)
- A.R.S. § 33-1126, Bank account (A)(9); life insurance, annuities and benefits (A)(1), (4), (6), (7); child support and spousal maintenance (A)(3); 529 plans (A)(10); EITC and child tax credits (A)(11); retirement plans (B); prepaid rent (C)
- A.R.S. § 33-1130, Tools of the trade
- A.R.S. § 33-1131, Wage garnishment limits
- A.R.S. § 33-1133(B), Arizona residents may not use the federal exemptions
Federal sources
- 11 U.S.C. § 522, Exemptions (domicile rule (b)(3)(A); federal list (d); homestead cap for recently acquired equity (p))
- 11 U.S.C. § 541, Property of the estate (property received within 180 days after filing, (a)(5))
- 42 U.S.C. § 407(a), Protection of Social Security benefits
- Judicial Conference, "Adjustment of Certain Dollar Amounts Applicable to Bankruptcy Cases," 90 Fed. Reg. 8941 (Feb. 4, 2025), effective April 1, 2025 ($214,000 homestead cap under § 522(p))
- U.S. Bureau of Labor Statistics, CPI-U, all items, U.S. city average, not seasonally adjusted (series CUUR0000SA0), August index values 2022–2025
Arizona courts
Call now: (480) 622-4987 Send the Bankruptcy Cats Signal
The Catizona Cattler, Debit and Biz are made-up cats, not lawyers, and not real clients. This column is general information, not legal advice, and reading it does not create an attorney-client relationship. Every case is different. Before you file bankruptcy, or move, sell or buy property, call Jeff Biddle Law at (480) 622-4987.