Can Mortgage Mediation in Chapter 13 Lower Your Payment in Arizona?
The short answer: Arizona’s Mortgage Modification Mediation program (MMM), under General Order 23-2, is a court-supervised way for people in bankruptcy to ask their mortgage lender for a loan modification. Individual Chapter 13 debtors (and Chapter 7 debtors whose cases were filed or converted on or after July 1, 2023) may qualify. It’s voluntary — the court won’t force a lender to modify — and any deal still needs court approval.
Fees and deadlines below are from the court’s current MMM procedures (rev. March 11, 2026).
The foreclosure stopped. Now what?
Filing Chapter 13 stopped the sale. Now comes the real question: what do you do about the mortgage itself? You've got two main choices, and I know them both. I'm Dark Whisker. I work in the shadows, and I'll take it from here.
Options for catching up on your mortgage
Think of your two choices as two restaurants across the street from each other. Whichever one you pick, the arrearage, meaning the missed payments, still has to be handled. The arrearage is the meal either way, and its size matters. A big arrearage is a big meal, and a small one might be a quick snack. You can't go fast food when you need a Thanksgiving feast. If you owe $50,000 in arrears, that's a feast-sized amount to handle. If you're only $2,000 to $3,000 behind, maybe a drive-thru works.
Catching up through the plan. The first restaurant keeps your loan as it is. The missed payments, called the arrears, are spread over your Chapter 13 plan, up to five years, while you keep making your regular mortgage payment. The bigger the meal, the bigger that monthly catch-up amount gets. If you're a few thousand dollars behind, it can be very manageable. If you're tens of thousands behind, the regular payment plus the catch-up can be more than your budget can carry.
Asking for a modification. The second restaurant asks the lender to change the loan itself, so the past-due amount is dealt with and the new monthly payment hopefully fits your budget. That's what the District of Arizona's Mortgage Modification Mediation program, or MMM, is for. It can be the better fit if you're far behind, or if the regular payment was already too much before you fell behind.
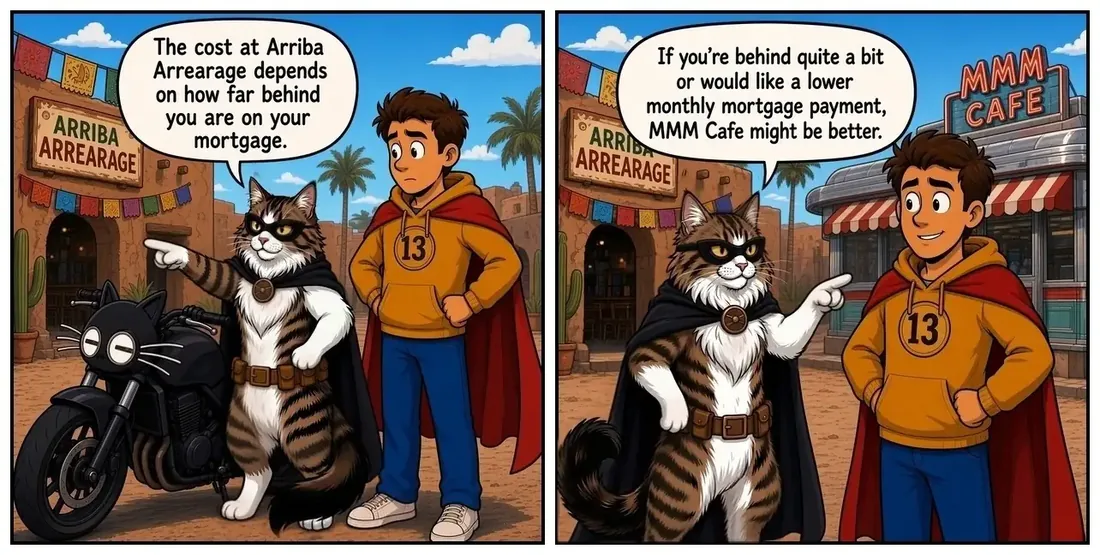
Both are good options but a bankruptcy attorney can explain both and help you choose.
| Topic | 🍽️ The Catch-Up Plate(through the plan) | ☕ The MMM Special |
|---|---|---|
| What happens to the loan | Terms stay the same | Lender may change rate, term, or how arrears are treated |
| Missed payments (arrears) | Spread over the Chapter 13 plan (up to five years) while you keep making the regular mortgage payment | Often rolled into the balance, set aside (forbearance), or handled with a partial claim on some government-backed loans |
| Payment while you work it out | Regular mortgage payment plus the catch-up (and your plan payment) | Estimated Monthly Payment through the trustee: the lesser of 31% of gross monthly income less HOA dues, or the regular mortgage payment (GO 23-2) |
| Can the court force a deal? | You’re curing arrears under the Bankruptcy Code; the loan itself isn’t rewritten | No — MMM is voluntary; the lender decides what to offer |
| When it often fits | Smaller arrears, or a regular payment you can already afford | Large arrears, or a payment that was already too high before you fell behind |
The MMM Cafe: the Mortgage Modification Mediation Program
MMM is a program run by the bankruptcy court in Arizona for Chapter 7 and 13 debtors who want to try for a loan modification on their home. It runs under General Order 23-2 (as revised March 11, 2026), which covers Chapter 13 cases and Chapter 7 cases filed or converted on or after July 1, 2023. It gives you a structured way to apply, a secure online portal where you and the lender trade documents, and a neutral mediator who helps both sides talk it through.
What it doesn't do is order the lender to modify your loan. The court can't make a lender say yes. The program gets everyone to the table, and the lender decides what it's willing to offer.
What paperwork does MMM take?
The first step is a modification application, which is a lot like a loan application. Expect to gather recent pay stubs or other proof of income, bank statements, tax returns, a hardship letter explaining what happened, and a budget. Your attorney then asks the court to refer your case to the program, and a mediator is assigned. While I've chosen to relate this to choosing between two restaurants, this is where it's different. You don't just order at the MMM Cafe. Giving the waitress the papers is like sending the ingredients to the kitchen.
There are some costs to keep in mind:
- $75 for the document preparation portal used to build the application package
- $75 for the MMM portal
- $300 for the mediator
Your attorney's fees for the program are separate. The court caps them, and they're usually paid through your Chapter 13 plan.
What do I pay while MMM is going on?
While mediation is going on, you make conduit mortgage payments (Local Rule 2084-4, as amended by General Order 23-4) to the Chapter 13 trustee in place of your regular mortgage payment. In Arizona, that payment is the lesser of 31% of your gross monthly income (less any HOA dues) or your regular mortgage payment (General Order 23-2; MMM Procedures § II(E)). It shows the lender you can handle a modified payment, and it keeps money going toward the house while everyone works it out.
What happens after the lender gets the paperwork?
Once the lender has reviewed your application, the mediator sets up a conference. Typically, once the lender has all of the initial paperwork from you, they process it and come back with a decision. It's basically like giving the waitress your ingredients and she gives them to the chef and you wait to see what they can make. The waitress brings it back and you decide if it's edible. You, your attorney, the lender's representative and the mediator talk through the lender's review and any offer. The program allows up to two of these conferences, about an hour each.
There's some room to negotiate. You can ask questions, point out mistakes in how your income was counted, or ask for different terms. Lenders usually have to follow their investor's guidelines, though, so there's often less give than people hope. You can always ask, and they can always say no.
Can I negotiate the lender’s offer?
At the MMM Cafe you don't really get a menu. You bring the ingredients, your paperwork, the waitress takes them to the chef, who is the lender, and she comes back with a dish. Then it's your call. It might be great, you might not want to eat it, or you might ask, "Can I have cheese on that?" You can send it back and ask for changes.
A modification usually mixes a few of these:
- A lower interest rate. Less sauce, and often the biggest drop in the payment.
- A longer term. Stretching the loan out, sometimes to 40 years, means smaller bites over a longer meal.
- Rolling the missed payments into the balance. The arrears go on the tab, so there's no separate catch-up.
- Principal forbearance. Part of the balance is set aside, interest-free, and comes due when the loan ends or the house is sold or refinanced. Think of it as dessert boxed up for later.
- A partial claim, on FHA loans and now VA loans. The past-due amount becomes a separate no-interest lien that's repaid when the loan is paid off, refinanced or the house is sold. Some VA servicers are still rolling this out.
- Principal reduction. It's on the menu, but it's rarely served.
One honest note: a modification doesn't always mean a lower payment. If the missed payments are rolled into the balance without a rate cut or longer term, the payment can stay about the same or even go up. What you get depends on what your lender's investor allows.
What are trial payments and the final deal?
Many lenders start with a trial period, often three months, at the new payment. Make those on time and the lender sends a final modification agreement. The court has to approve the modification before it's final, and your Chapter 13 plan is updated to match.
Mediation can run up to 150 days from the court's referral order. Lenders aren't always quick, and the service can be slow.
What if there’s no offer, or I don’t like it?
You don't have to accept an offer that doesn't work for you. And sometimes the lender doesn't offer anything at all. Either way, if mediation ends without a deal, you file an amended plan within 28 days. You could go back to the other restaurant, Arrearage, and catch up the arrears through the plan if the payment fits your budget. If it doesn't, you could surrender the house, or you could sell it. Either way, any shortfall left after it's sold is handled with your other unsecured debts in the plan. It's not the outcome anyone hopes for, but it's a real choice, and your attorney can help you weigh it gently and honestly.
So that's the MMM Cafe, SuperHomey. Order what you need, be patient with the kitchen, and know there's always another road if the meal isn't right. Jeff's the one who helps you figure out which road fits, and gets your order in.
Behind on your mortgage in Phoenix or anywhere in the Valley and wondering about a modification? Reach out to Jeff Biddle Law (and the Bankruptcy Cats).
Call now: (480) 622-4987 Send the Bankruptcy Cats Signal
Mmm… worth the wait.
MMM Cafe FAQ
Who qualifies for Arizona’s MMM program?
Individual debtors with a pending Arizona bankruptcy case in Chapter 13 (or Chapter 11/12), or in Chapter 7 if the case was filed under Chapter 7 or converted to Chapter 7 on or after July 1, 2023. You also need to be able to pay the program fees up front and have enough income for the Estimated Monthly Payment (plus any Chapter 13 plan payment).
What does MMM cost?
Under the court’s current procedures: $75 for the document-preparation software (docUmods), $75 for the MMM portal submission, and $300 for the debtor’s half of the $600 mediator fee. Court-capped attorney fees for the program are generally up to $3,000 plus $100 in costs for newer referrals (older referrals may still use the prior $2,500 cap), and in Chapter 13 those fees are usually paid through the plan.
What’s the deadline to ask for a referral?
In Chapter 7, request referral within 45 days after filing the petition, or within 30 days after an order converting the case to Chapter 7 (if you didn’t already participate in MMM before conversion). In Chapter 13, you can seek referral before or after plan confirmation; file the initial/amended/modified plan with the Motion for Referral as the procedures require.
How long does MMM take?
The program is generally supposed to finish within 150 days after the court enters the referral order, unless the parties extend it on the portal or the court orders more time. A trial modification can automatically extend that window.
What if there’s no offer, or I don’t like the offer?
You don’t have to accept a bad offer, and sometimes the lender offers nothing. If mediation ends without a deal in Chapter 13, you generally file an amended or modified plan within 28 days. Options can include catching up the arrears through the plan, surrendering the house, or selling it — your attorney can help weigh those.
Flare Explains
Arrears: The missed payments, fees and charges owed on the mortgage when the case was filed.
Loan modification: A permanent change to the terms of your mortgage, such as the rate, the term or the balance, agreed to by the lender.
Mediator: A neutral person who helps you and the lender talk. The mediator doesn't decide anything and doesn't represent either side.
Conduit mortgage payments: The monthly payments you make to the Chapter 13 trustee, in place of your regular mortgage payment, while mediation is going on.
Trial period: A few months of payments at the proposed new amount before the modification becomes final.
Partial claim: A separate no-interest lien, available on some government-backed loans, that covers the past-due amount and is repaid at the end of the loan.
Surrender: Giving the house back to the lender through the plan, so the mortgage is no longer paid.
Where this comes from
- Arizona's Mortgage Modification Mediation program, its fees, the mediation payment, conferences and the 28-day amended plan: U.S. Bankruptcy Court, District of Arizona, Mortgage Modification Mediation (General Order 23-2, as revised March 11, 2026).
- Catching up mortgage arrears through a plan: 11 U.S.C. § 1322(b)(5) and (c)(1).
- Arizona mortgage payments through the trustee: Local Rule 2084-4.
- Conduit payments during mediation: General Order 23-4, which amended Local Rule 2084-4 and MMM Procedures § III.
- Changing a confirmed plan: 11 U.S.C. § 1329.
- VA partial claims: VA Partial Claim Program announcement.
Written October 2026. This post reflects the law and court rules as of that date, and they change. It's general information, not legal advice, and reading it doesn't create an attorney-client relationship. For advice about your situation, talk with a bankruptcy attorney licensed where you live.