Chapter 7 in Arizona: Lightning Wipeout's Dream Date & Deal Breakers
Serving Chandler and the Phoenix metro area
Part of Lightning Wipeout’s Chapter 7 interview
Lightning Wipeout's Dream Date
"Picture this, babe. You've got steady bills you can't keep up with, mostly credit cards and medical debt, and nothing fancy to lose. We meet on a Monday.
By that afternoon the garnishment's paused and the collectors have lost your number.
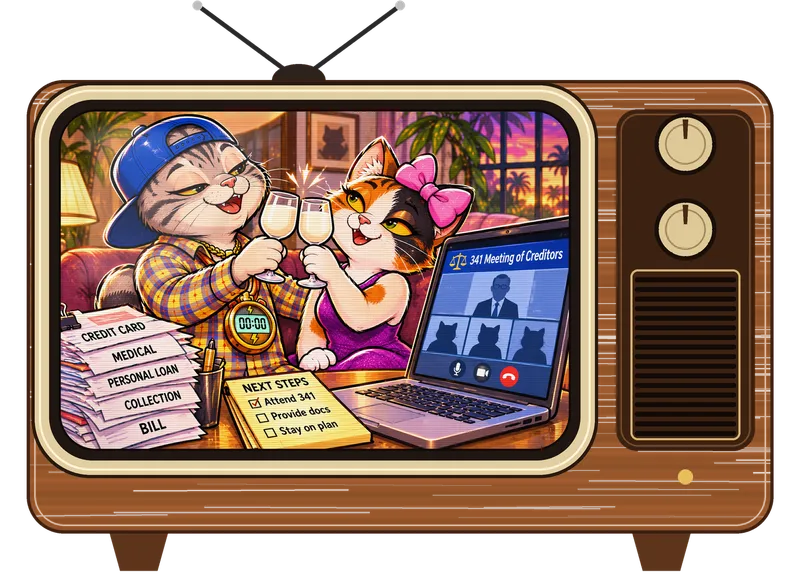
About a month later we have a quick Zoom date with the trustee, no drama, nothing to sell.
Around month four the discharge comes through, I kiss you on the forehead, and I'm gone.
You wake up debt-free and a little confused about how fast it all happened. Best four months of your life."
His Deal Breakers
These seven situations can keep Chapter 7 from working for you, and here is what each one means.
Can I file Chapter 7 if I earn too much?
If your income is over Arizona's median for your household size and the means test doesn't work out, you may not qualify for Chapter 7 (11 U.S.C. § 707(b)). A detailed expense calculation decides.
For cases filed on or after December 1, 2026, here are Arizona's median family income figures:
| Household size | Median family income |
|---|---|
| 1 person | $75,555 |
| 2 people | $90,617 |
| 3 people | $101,269 |
| 4 people | $122,032 |
| Each person over 4 | Add $11,100 |
Last checked November 20, 2026. Source: U.S. Trustee median income table.
Lightning says: “You earn too much.”
Can I file Chapter 7 twice?
You can't get a second Chapter 7 discharge until 8 years from your last Chapter 7 filing (11 U.S.C. § 727(a)(8)), counted from the filing date of the first case to the filing date of the new one.
Lightning says: “You've been with me in the last 8 years.”
Can I catch up on my house or car in Chapter 7?
No. Chapter 7 can pause a foreclosure or repossession, but it has no plan to catch up on missed payments and won't help with back payments. That's Chapter 13's job.
Lightning says: “You want to catch up on the house or car.”
Can I keep my property in Chapter 7?
Only up to Arizona's exemptions. If you have equity above them, the trustee can sell the extra. Exemptions protect your equity, not the total value.
Lightning says: “You've got pricey stuff I can't protect.”
Which debts survive Chapter 7?
Domestic support, most recent taxes and student loans (unless you prove undue hardship) stick around after discharge, along with government fines and penalties (11 U.S.C. § 523).
Lightning says: “Your exes are support, student loans or new taxes.”
What happens if I hide something in Chapter 7?
Fraud, hidden assets or a fraudulent tax return can end the case, and they can cost you the discharge.
Lightning says: “You're hiding something.”
Does Chapter 7 protect my cosigner?
No. Chapter 7 protects only you. Your cosigner still owes the debt.
Lightning says: “You need a cosigner protected.”
| Deal breaker | Why it matters | What to do |
|---|---|---|
| Earns too much | Your average income over the last six months, annualized, is compared to Arizona's median for your household size. If it's over, a detailed expense calculation decides. | Ask an Arizona bankruptcy attorney to run the means test. Chapter 13 (steady income, three-to-five-year commitment) may fit instead. |
| Chapter 7 discharge within 8 years | No second Chapter 7 discharge until 8 years from your last Chapter 7 filing. You can technically file sooner, but you won't get a discharge. | Count 8 years from the filing date of the first case to the filing date of the new one. |
| Wants to catch up on a house or car | The mortgage lien survives, the lender can ask the court for stay relief, and Chapter 7 has no plan to catch up on missed payments. | Look at Chapter 13, which gives you three to five years to catch up. |
| Equity above exemptions | The trustee can sell nonexempt property, meaning equity above Arizona's exemptions. | Compare your equity to Arizona's 2026 exemptions: about $437,600 of home equity, $16,500 in one vehicle (about $27,500 with a qualifying disability) and $5,600 in one bank account. Many Arizona cases have nothing to sell. See Arizona's 2026 exemption table. |
| Support, student loans or recent taxes | These debts survive Chapter 7 (11 U.S.C. § 523). | Expect them to stay. Student loans are wiped out only if you prove undue hardship. |
| Hiding something | Fraud, hidden assets or a fraudulent tax return can end the case and cost you the discharge. | Disclose everything. The trustee asks you questions under oath at the 341 meeting. |
| Needs a cosigner protected | Chapter 7 protects only you. Your cosigner still owes the debt. | Talk to an Arizona bankruptcy attorney before you file. |